Palm payments, built into your bank.
HathPay is the enrolment, matching and device layer that lets a bank's customers pay with the palm of their hand. The bank keeps the customer, the account and every rupee that moves.
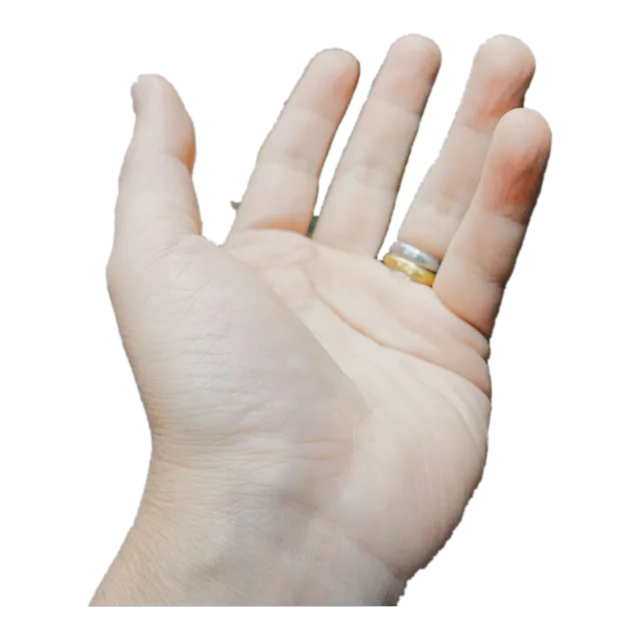
A real palm photo run through HathPay's pipeline: the landmarks, the palm region and the orientation code shown are what the software computed.
The customer never installs anything new.
HathPay lives inside the bank's own app, at the bank's branches and at the merchants the bank already serves.
Switch it on
Consent, the account to pay from and a separate HathPay PIN, inside the app the customer already trusts.
Register the palm
Staff check identity. A near-infrared terminal takes five captures and keeps only a template.
Pay by hand
The customer holds out a palm. The bank authorises the debit and moves the money.
HathPay in one minute.
From switching it on in a bank app to the bank settling the payment.
Hold out your hand. That is the checkout.
The customer never touches the terminal. The palm is read from above in near-infrared light, the bank approves, and the confirmation lands in the bank's app a moment later.
- No phone, card, cash or contact
- HathPay PIN only for larger or unusual payments
- Instant confirmation in the customer's bank app
Your brand on the screen. Your ledger behind it.
The HathPay module appears inside the bank's app in the bank's colours. At the till, the terminal identifies the palm and the bank's own systems decide. Every result reaches the bank as a signed event.
Everything a bank would ask about, answered in the product.
Security first
Templates instead of images, per-bank encryption keys, signed terminals and single-use request signatures.
Security →A small integration
Two adapter endpoints and a webhook receiver. Use our module in your app, or build your own screens on our APIs.
Developers →Near-infrared hardware
Terminals read the vein pattern under the skin, which a photograph of a hand does not show.
Hardware →Priced as infrastructure
Platform licence, terminals as a service and integration, with an optional usage component.
For banks →Clear architecture
Four separate API surfaces, six platform services and two narrow contracts with the bank.
Architecture →Honest progress
What is finished, what is in progress and what we will prove before any real money moves.
Status →See it working, end to end, in thirty minutes.
Activation in a bank app, enrolment at a branch terminal and a palm payment settled through a simulated bank. Then the architecture and the pilot plan.